Ever wondered how much auto insurance costs in Massachusetts? You’re not alone. Navigating the world of car insurance can be as tricky as Boston’s infamous road layout. But don’t worry, we’re here to decode everything for you—from the basic requirements to insider tips on scoring the best rates. Fasten your seatbelt and let’s dive into the essentials of auto insurance in the Bay State.
In Massachusetts, having car insurance isn’t just a good idea—it’s the law. Understanding what you need, what affects your rates, and where to find savings can make all the difference. Whether you’re a lifelong local or a newcomer, this guide will equip you with the knowledge you need to drive confidently and cost-effectively.
Overview of Auto Insurance in Massachusetts
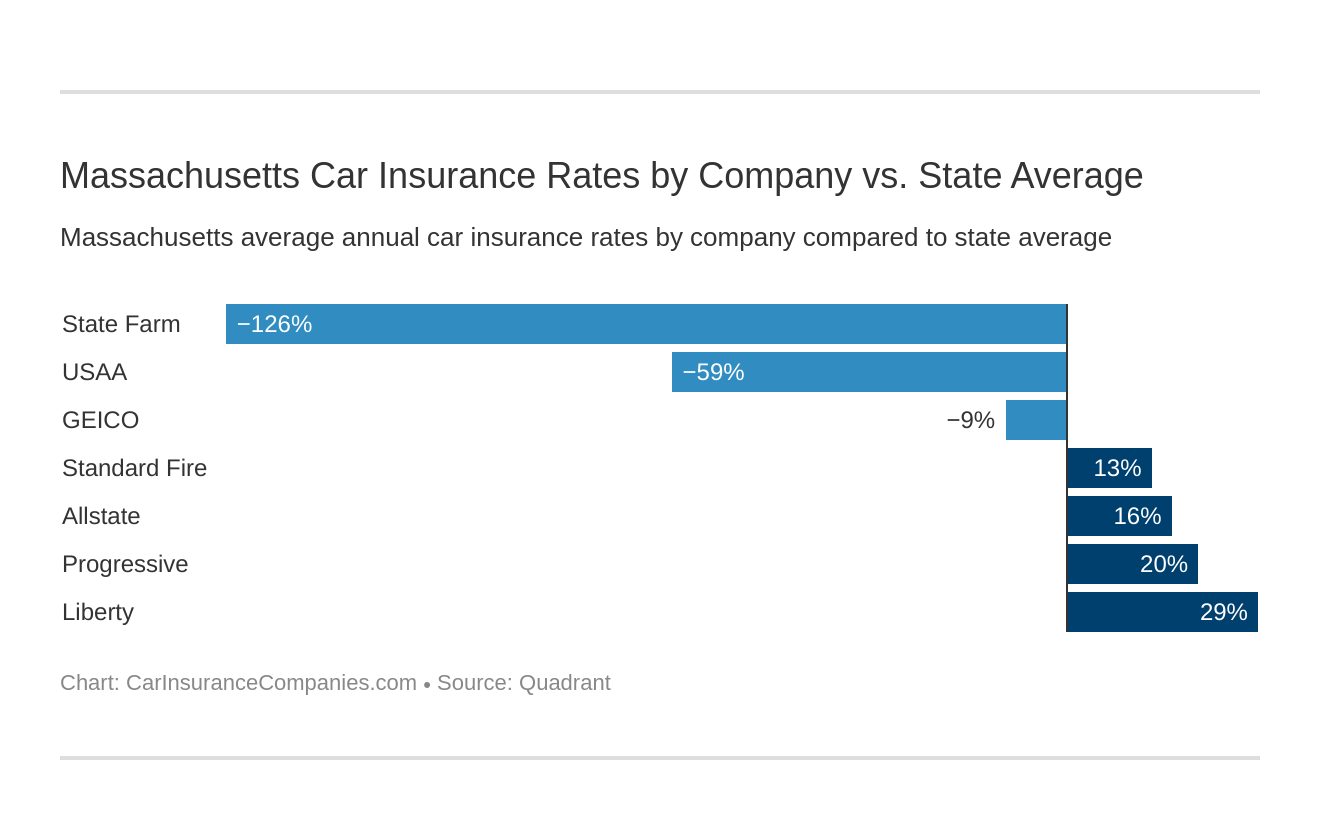
Did you know that Massachusetts boasts some of the toughest auto insurance laws in the U.S.? If you’re driving in the Bay State, there’s a lot you need to know.
When it comes to auto insurance here, you simply can’t skip the basics. Massachusetts requires drivers to carry specific minimum insurance coverage. But that’s just the tip of the iceberg.
Basic Requirements for Auto Insurance
Every driver must have a certain level of insurance to hit the road legally. In Massachusetts, this means carrying at least bodily injury liability and property damage liability. You’re looking at minimums like $20,000 per person and $40,000 per accident for bodily injury.
Here is the deal: it’s not just about meeting the state’s requirements. It’s about protecting yourself financially from the unexpected.
Types of Coverage Available
You might think you’re all set with the minimums. BUT, that might leave you exposed. Let’s dive into the types of coverage you can choose from:
- Comprehensive Coverage: Protects against non-collision related damage such as theft or weather damage.
- Collision Coverage: Covers damage from accidents regardless of who is at fault.
- Uninsured/Underinsured Motorist Coverage: Offers protection when the other party doesn’t have enough insurance.
Pro Tip: Consider adding comprehensive and collision if your car is less than 10 years old or financed.
The Role of Minimum Coverage
Minimum coverage isn’t just a box to check. It’s a legal requirement, and it plays a critical role in your financial protection strategy. Here’s why:
If you cause an accident, you could be liable for damages beyond what your policy covers. The minimum ensures you’ve at least got some cushion against massive financial fallout.
But, remember, the minimum might still leave you on the hook for thousands if a serious accident occurs. It’s worth considering higher limits to really safeguard your assets.
Factors Influencing Auto Insurance Costs
Did you know that your auto insurance premium in Massachusetts can fluctuate based on several key factors? These factors not only affect how much you pay but also determine the coverage you’ll receive.
The cost of auto insurance isn’t just a random number. It’s influenced by a mix of personal and geographical variables that insurers use to assess risk. Whether you’re cruising through downtown Boston or zipping along Cape Cod, these factors come into play.
Impact of Driving History on Insurance Premiums
Your driving history is like your resume for auto insurers. If you’ve had accidents, speeding tickets, or DUIs, brace yourself for higher premiums. Insurers see you as a higher risk, which translates into increased costs. BUT, if you have a squeaky clean record, you could qualify for some sweet discounts.
Think of it this way: insurers reward safe drivers. So, maintaining a clean driving record not only keeps you safe but also saves you cash.
Role of Location in Determining Insurance Rates
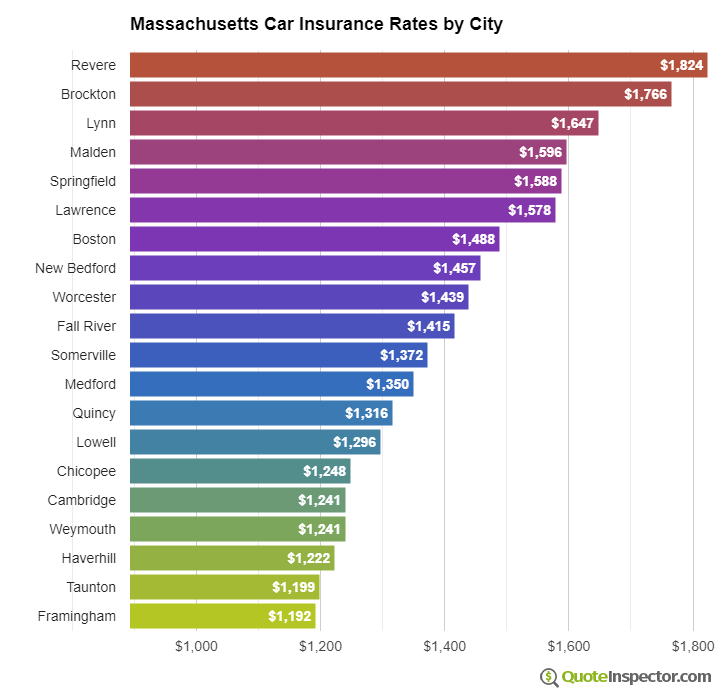
Your location has a huge impact on what you’ll pay. Living in a congested city like Boston means more traffic and a higher likelihood of accidents, which can spike your rates. On the flip side, reside in a quieter, rural area? Enjoy potentially cheaper premiums.
Here’s the deal: Insurers look at crime rates, traffic patterns, and even weather conditions when determining your location-based costs. So, while you can’t always choose where you live, knowing this can help you understand your bill better.
Pro Tip: If you’re looking to move, consider the insurance implications of your new area. A few miles can mean a significant change in rates!
Average Cost of Auto Insurance
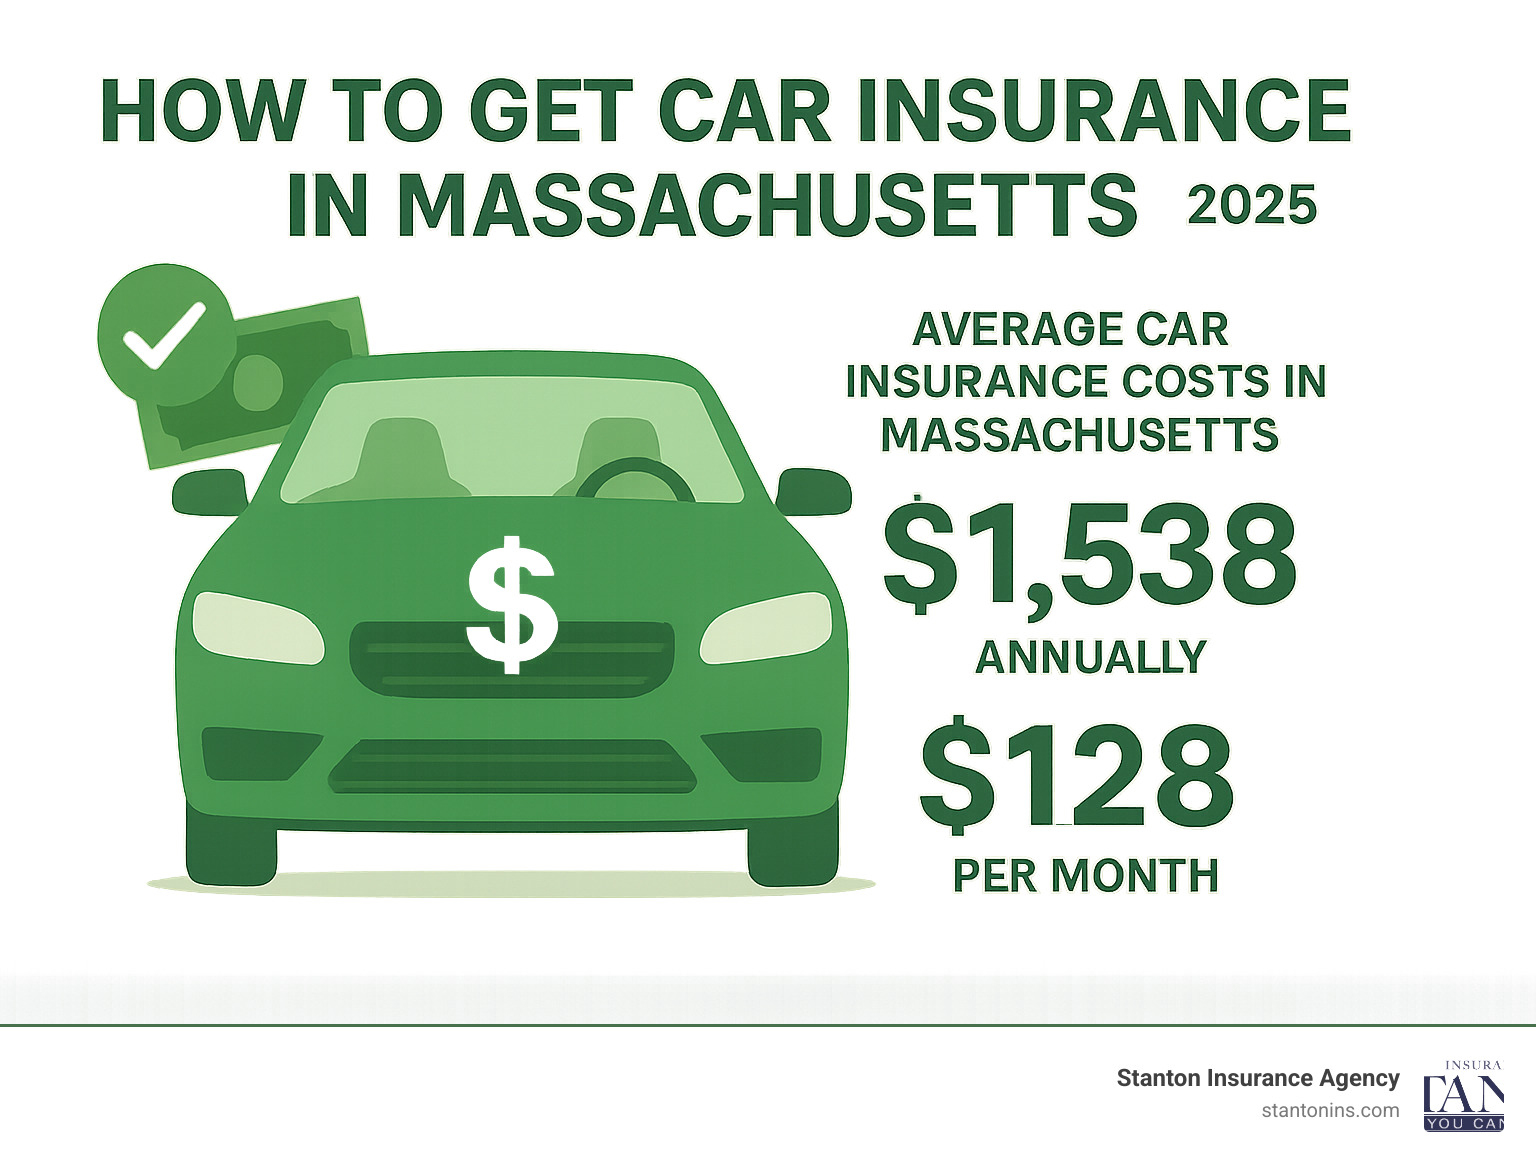
Let’s talk dollars and cents. Did you know that Massachusetts drivers pay an average of $1,223 annually for auto insurance? This number might seem hefty, but it’s significantly influenced by a variety of factors we’ll dive into.
When you compare this to the national average, Massachusetts is on the higher end of the spectrum. BUT, before you start worrying, remember that several factors can tweak this number up or down, depending on your situation.
Cost Comparisons: Massachusetts vs. National Averages
If you’re curious about how Massachusetts stacks up against the rest of the country, take a look at this: while the national average sits at about $1,070, Massachusetts drivers face a bit more pressure on their wallets. Here is the deal: these costs aren’t just random numbers. They reflect Massachusetts’ unique regulations and coverage requirements.
| Location | Average Annual Cost |
|---|---|
| Massachusetts | $1,223 |
| National | $1,070 |
Variation in Costs Based on Coverage Options
Here’s where it gets interesting: your insurance cost isn’t just about where you live. It’s also about the type of coverage you choose. For instance, a basic liability plan will be much lighter on your pocket compared to a comprehensive plan that covers everything from theft to natural disasters.
So, how do you decide? It all boils down to your needs and risk tolerance. If you’re driving an older car, you might opt for less coverage. BUT, if you’ve just bought a new ride, comprehensive coverage might be your best friend. Remember:
Pro Tip: More coverage means more peace of mind, but also a higher premium. Choose wisely!
Discounts and Savings Opportunities
Want to slash your auto insurance bill? You’re in luck because Massachusetts is loaded with discounts and savings opportunities.
Insurance companies are itching to offer you deals. The trick? Know what discounts are available and how to snag them.
Common Discounts Offered by Insurance Providers
The discounts can be a goldmine. Many insurers in Massachusetts provide good driver discounts for maintaining a clean driving record. Then, there’s the multi-policy discount where bundling home and auto insurance can save you serious cash.
Some companies offer low mileage discounts if you drive less than a set amount each year. And don’t forget about student discounts for those who ace their grades.
Methods to Qualify for Discounts
So, how do you qualify for these money-saving deals? It’s simpler than you think. To qualify for a good driver discount, keep your driving record spotless. No tickets or accidents, and you’re golden.
For multi-policy discounts, it’s all about consolidation. Combine your insurance under one roof. And if you’re a student, keep those grades high, and you could see a nice discount.
Maintaining a Clean Driving Record
Want to keep more cash in your pocket? Here’s the deal: drive safely. A clean record isn’t just about avoiding traffic tickets. It’s about showing insurers you’re responsible. That means fewer claims and more discounts.
Here’s a pro tip:
Enroll in a defensive driving course. Not only will you improve your skills, but many insurers offer a discount for completing it.
This is a simple step to ensure your driving record remains immaculate.
How to Choose the Right Insurance Provider
Choosing the right auto insurance provider in Massachusetts can feel like searching for a needle in a haystack. You’ve got tons of options, but how do you know which one is right for you?
Here is the deal: Not all providers are created equal. You need to consider several key factors to ensure you’re getting the best coverage at a price that won’t break the bank. Let’s dive into what you should look out for when evaluating your options.
Criteria for Selecting an Insurance Provider in Massachusetts
First things first, focus on the reputation and financial stability of the insurer. You want a provider that’s not only reliable but also financially sound to pay out claims when you need them. Check their ratings with agencies like AM Best or Standard & Poor’s to get a sense of their solvency.
Next, look at their policy offerings and flexibility. The best providers will offer a variety of coverage options and allow you to customize a plan that fits your specific needs. If you drive an electric vehicle or have a teen driver in the family, make sure they offer specialized coverage or discounts.
The Importance of Customer Service and Claims Handling
Good customer service can make or break your insurance experience. You want a provider with a track record of excellent customer support and fast claims processing. Ask friends and family about their experiences or check online reviews to get a feel for how a provider treats its customers.
Also, don’t underestimate the power of easy claims handling. A provider that offers a streamlined, efficient claims process can save you a lot of headaches. Look for options like mobile app claims filing or 24/7 claims support.
Questions to Consider When Evaluating a Provider
Before making your choice, ask yourself the following questions:
- Does the provider have good customer reviews?
- Are there any discounts available that apply to me?
- How quickly do they handle claims?
- What is their financial stability rating?
- Do they offer the coverage options I need?
Pro Tip: Always compare at least three different providers to ensure you’re getting the best deal.
Recent Changes and Trends in Massachusetts Auto Insurance
Are you aware of the latest shifts in Massachusetts auto insurance? Recent legislative changes and tech innovations are shaking things up.
Massachusetts auto insurance is evolving. New laws and emerging technologies are creating waves. Here’s how these changes could impact your policy and premiums.
Legislative Changes Impacting Auto Insurance
A recent legislative change mandates increased minimum liability coverage. This change aims to offer better protection but could lead to higher premiums for drivers. Lawmakers believe it’s a necessary step for adequate coverage, but your budget might feel the pinch.
Here’s the deal: Higher coverage limits typically mean greater protection on the road, but they can also mean a heavier financial burden.
Emerging Trends in the Auto Insurance Market
Telematics and usage-based insurance are gaining traction. More insurance companies are offering policies that use real-time data to determine premiums. This trend rewards safe drivers but can penalize those with less-than-perfect habits.
Step #1: Consider enrolling in a usage-based program if you drive safely and infrequently. These programs can potentially lower your premiums with positive driving behavior.
Pro Tip: Always read the fine print on how mileage and driving habits are tracked. Hidden fees might lurk!
The Impact of Technology on Auto Insurance Policies
Technology is transforming the insurance landscape. From AI-driven claim processing to advanced mobile apps, insurers are leveraging tech to enhance customer experience. One standout is the use of artificial intelligence in evaluating claims, reducing the need for lengthy manual reviews.
Step #2: Embrace mobile technology for easier management of your policy. Many insurers offer apps that streamline everything from payments to claims.
But remember, while tech offers convenience, it also introduces privacy concerns. Always ensure your data is secure with your chosen provider.
Final Summary
Alright, now you’ve got the full scoop on auto insurance in Massachusetts. From the nuts and bolts of coverage options to the variables that steer your premium costs, you’re ready to make informed decisions. Remember, the right coverage not only keeps your ride legal but also protects your wallet and peace of mind. Happy driving!
FAQ
What are the minimum auto insurance requirements in Massachusetts?
In Massachusetts, drivers are required to have a minimum level of coverage that includes Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property.
How does my driving history affect my insurance rates?
A clean driving record can significantly lower your insurance premiums, while a history of accidents or violations can increase costs.
Does my location within Massachusetts impact my auto insurance cost?
Yes, where you live can affect your insurance rates. Urban areas with higher traffic and crime rates typically have higher premiums compared to rural areas.
What are common discounts offered by Massachusetts insurance providers?
Common discounts include those for good drivers, multiple policies, students with good grades, and vehicles equipped with safety features.
How can I choose the right auto insurance provider in Massachusetts?
Consider factors such as customer service, claims handling, financial stability, coverage options, and available discounts. It’s also wise to read reviews and ask for recommendations.
Are there any recent changes in Massachusetts auto insurance legislation?
Recent changes may include updates to minimum coverage requirements or regulations affecting insurance premiums. Staying informed about legislative changes is crucial.
