Are you tired of paying sky-high insurance premiums in North Carolina? You’re not alone! Navigating the insurance landscape can be as daunting as finding a needle in a haystack. But fear not, because we’re here to unravel the complexities and help you uncover the best insurance rates in NC.
In this detailed guide, we’ll dive into the nitty-gritty of what influences insurance rates across the Tar Heel State. From demographic shifts to city-specific comparisons, you’ll gain insights that are both actionable and transformative. So buckle up and get ready to save!
Understanding Insurance Rates in North Carolina
Did you know that your car insurance rate in North Carolina could jump by as much as 50% just based on where you live? That’s right! Understanding the factors affecting insurance rates here can save you hundreds.
Insurance rates across North Carolina aren’t just numbers pulled out of a hat. They’re based on a complex formula that insurers use to gauge risk. The costs can vary significantly depending on your location, age, and even personal habits.
Factors Affecting Insurance Rates in NC
There are several key elements at play when determining your insurance rates in NC. First off, your driving record is a major player. A spotless record? You’re golden. But a few speeding tickets? Expect to pay more. Then there’s your credit score. Yes, it influences your rates, too!
Other factors include the type of vehicle you drive, how often you drive it, and where you park it at night. City dwellers often face higher rates due to increased traffic and crime rates. Meanwhile, rural residents may benefit from lower premiums. Understanding these factors can help you make smarter choices and potentially lower your insurance costs.
Comparison of Insurance Rates Across Different Cities in NC
Here’s the deal: Not all cities are created equal when it comes to insurance rates. Let’s look at a comparison across major cities in North Carolina:
| City | Average Annual Rate |
|---|---|
| Charlotte | $1,200 |
| Raleigh | $1,100 |
| Greensboro | $1,050 |
| Durham | $1,150 |
| Wilmington | $1,080 |
As you can see, Charlotte tops the list with an average annual rate of $1,200. If you’re in Greensboro, you might enjoy slightly lower rates. But even within cities, different neighborhoods can have varied rates due to local factors like crime rates and traffic congestion.
Impact of Demographic Changes on Rates
Demographics can play a surprising role in insurance rate fluctuations. For instance, young drivers (under 25) often face steeper premiums due to perceived risk. Women generally pay less than men because statistics show they’re involved in fewer accidents.
Pro Tip: If you’re a student with good grades, you might qualify for a “good student discount.” Also, as you age and gain more driving experience, your rates tend to decrease assuming you keep a clean driving record.
More people moving into urban areas can lead to higher rates due to increased traffic and accidents. On the flip side, an aging population might see a shift in pricing strategies as older drivers tend to present a different set of risk factors.
Types of Insurance Available in NC
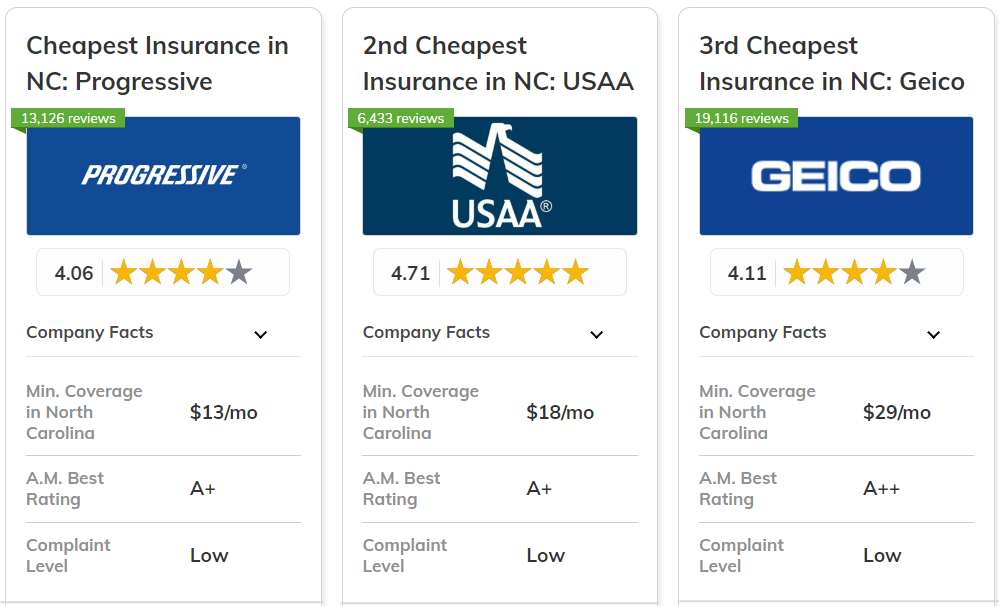
Did you know that North Carolina is home to a diverse range of insurance options? Whether you’re looking for auto, home, health, or life insurance, there’s something for everyone here.
The state offers a variety of policies to fit your needs. Understanding these options can help you make more informed decisions and snag the best rates.
Auto Insurance Options
In North Carolina, auto insurance is mandatory, and you have several coverage types to choose from. The three most common types are liability, comprehensive, and collision coverage. Liability coverage is the bare minimum, covering damage to others if you’re at fault. Comprehensive covers non-collision-related damages like theft or natural disasters. Collision coverage handles the cost of repairs to your car after an accident. But here’s the deal: the right choice depends on your vehicle, driving habits, and budget.
Pro Tip: Combine comprehensive and collision for more robust protection.
Home Insurance Policies
Home insurance in NC protects your home from unforeseen events like fires, storms, and theft. Most policies offer a combination of dwelling, personal property, and liability protection. But the key is to ensure your policy covers specific risks prevalent in your area. Flood insurance, for example, may be necessary for coastal regions.
Health and Life Insurance
Your health is your wealth, and North Carolina has you covered with diverse health insurance plans. From HMOs to PPOs, you can find a plan that suits your medical needs and budget. Life insurance is equally important. Choose between term life policies, which offer protection for a specific period, and whole life policies that include a savings component.
Here’s a quick comparison of different insurance providers and what they offer in NC:
| Provider | Auto Insurance | Home Insurance | Health Insurance | Life Insurance |
|---|---|---|---|---|
| Provider A | Liability, Comprehensive | Standard, Flood | HMO, PPO | Term, Whole |
| Provider B | Collision, Comprehensive | Dwelling, Liability | PPO, HSA | Universal, Term |
| Provider C | Liability, Collision | Standard, Additional Riders | HMO, EPO | Whole, Universal |
Finding the Best Insurance Rates

Did you know that 90% of people are overpaying for their insurance policies? It’s true! But finding the best insurance rates in North Carolina doesn’t have to be a headache.
The secret lies in knowing where to look and how to negotiate. Here’s the deal: you can save hundreds, even thousands, by following a few strategic steps.
Researching and Comparing Insurance Rates
Step #1: Start by gathering quotes from multiple providers. Don’t settle for the first offer. Use comparison tools like NerdWallet or The Zebra to get a sense of the market. These tools can help you spot big price differences.
Step #2: Evaluate coverage options carefully. A cheaper policy might leave out essential coverage that could cost you more in the long run. Always check the fine print.
Pro Tip:
Sign up for newsletters from insurance companies for exclusive discounts and promotions.
Negotiating Lower Premiums
After researching, it’s time to negotiate. Start with your current insurer. You’d be surprised how often you can snag a better deal just by asking.
Step #1: Highlight your loyalty. Insurers value long-term customers. Use this to your advantage and ask for a loyalty discount. Step #2: Present competing offers. Having quotes from other companies gives you leverage.
Remember, the key is to be prepared and persistent. Don’t take no for an answer on your first try!
Leveraging Online Tools for Rate Comparisons
Online comparison tools are your best friends. They do the heavy lifting by aggregating data from multiple insurers and presenting them side by side.
Use sites like Insure.com or Policygenius for detailed comparisons. These platforms provide insights not just into rates, but also into customer satisfaction and coverage details. Less time, more savings.
Pro Tip:
Set up alerts on these platforms to notify you of rate changes or special deals.
Top Insurance Providers in NC
Did you know that over 65% of North Carolinians are dissatisfied with their insurance providers? That’s a staggering number! The good news is, finding the right provider can save you big time.
The key is to find the best combination of pricing, coverage, and customer satisfaction. Let’s dive into the top insurance providers in North Carolina and see how they stack up against each other.
Leading Insurance Providers in North Carolina
When it comes to insurance in NC, a few names consistently come up. Here are the top contenders:
- State Farm
- GEICO
- Nationwide
- North Carolina Farm Bureau
- Progressive
These providers consistently receive high marks for their coverage options and customer service. BUT, how do they really compare in terms of customer satisfaction?
Customer Reviews and Satisfaction Ratings
Here’s the deal: customer satisfaction can make or break your insurance experience. Let’s see who comes out on top according to real customer reviews.
| Provider | Customer Rating | Coverage Options | Pricing |
|---|---|---|---|
| State Farm | 4.5/5 | Comprehensive | Moderate |
| GEICO | 4.2/5 | Basic to Comprehensive | Low |
| Nationwide | 4.0/5 | Extensive | Moderate to High |
| North Carolina Farm Bureau | 4.4/5 | Focused on Local Needs | Competitive |
| Progressive | 4.1/5 | Wide Range | Variable |
Pro Tip: Always read customer reviews before choosing an insurance provider. Real experiences can reveal hidden fees or exceptional service.
Remember, the best provider is the one that meets your specific needs and budget. Evaluate their strengths and weaknesses to make an informed decision.
Tips for Lowering Your Insurance Rates
Craving lower insurance rates? You’re not alone. The average American spends over $1,500 annually on car insurance alone. BUT, there are proven methods to cut those costs!
Let’s dive into strategies that can trim your premiums while keeping you covered. It’s all about smart choices and knowing the right moves.
Maintain a Stellar Driving Record
Think of your driving record as your insurance credit score. A clean driving record can make a massive difference in your premiums. Insurance companies reward drivers who steer clear of tickets, accidents, and claims.
Avoiding traffic violations isn’t just about safety; it’s about savings too. If you’re prone to speeding, it might be time to reign it in. Over time, these efforts can lead to significant reductions in what you pay.
Pro Tip: Enrolling in a defensive driving course can often secure you a discount.
Bundle Policies for Maximum Discounts
Ever heard of the term “bundling”? It’s not just for TV subscriptions. Combining different types of insurance policies with the same provider can lead to substantial discounts.
For example, if you have both home and auto insurance, consider bundling them. Insurance companies love loyal customers, and by keeping all your policies under one roof, you often get rewarded.
Here is the deal, the savings from bundling can be anywhere from 5% to 25%. That’s money back in your pocket for something as simple as a policy review.
Legislation and Regulations Affecting Insurance Rates
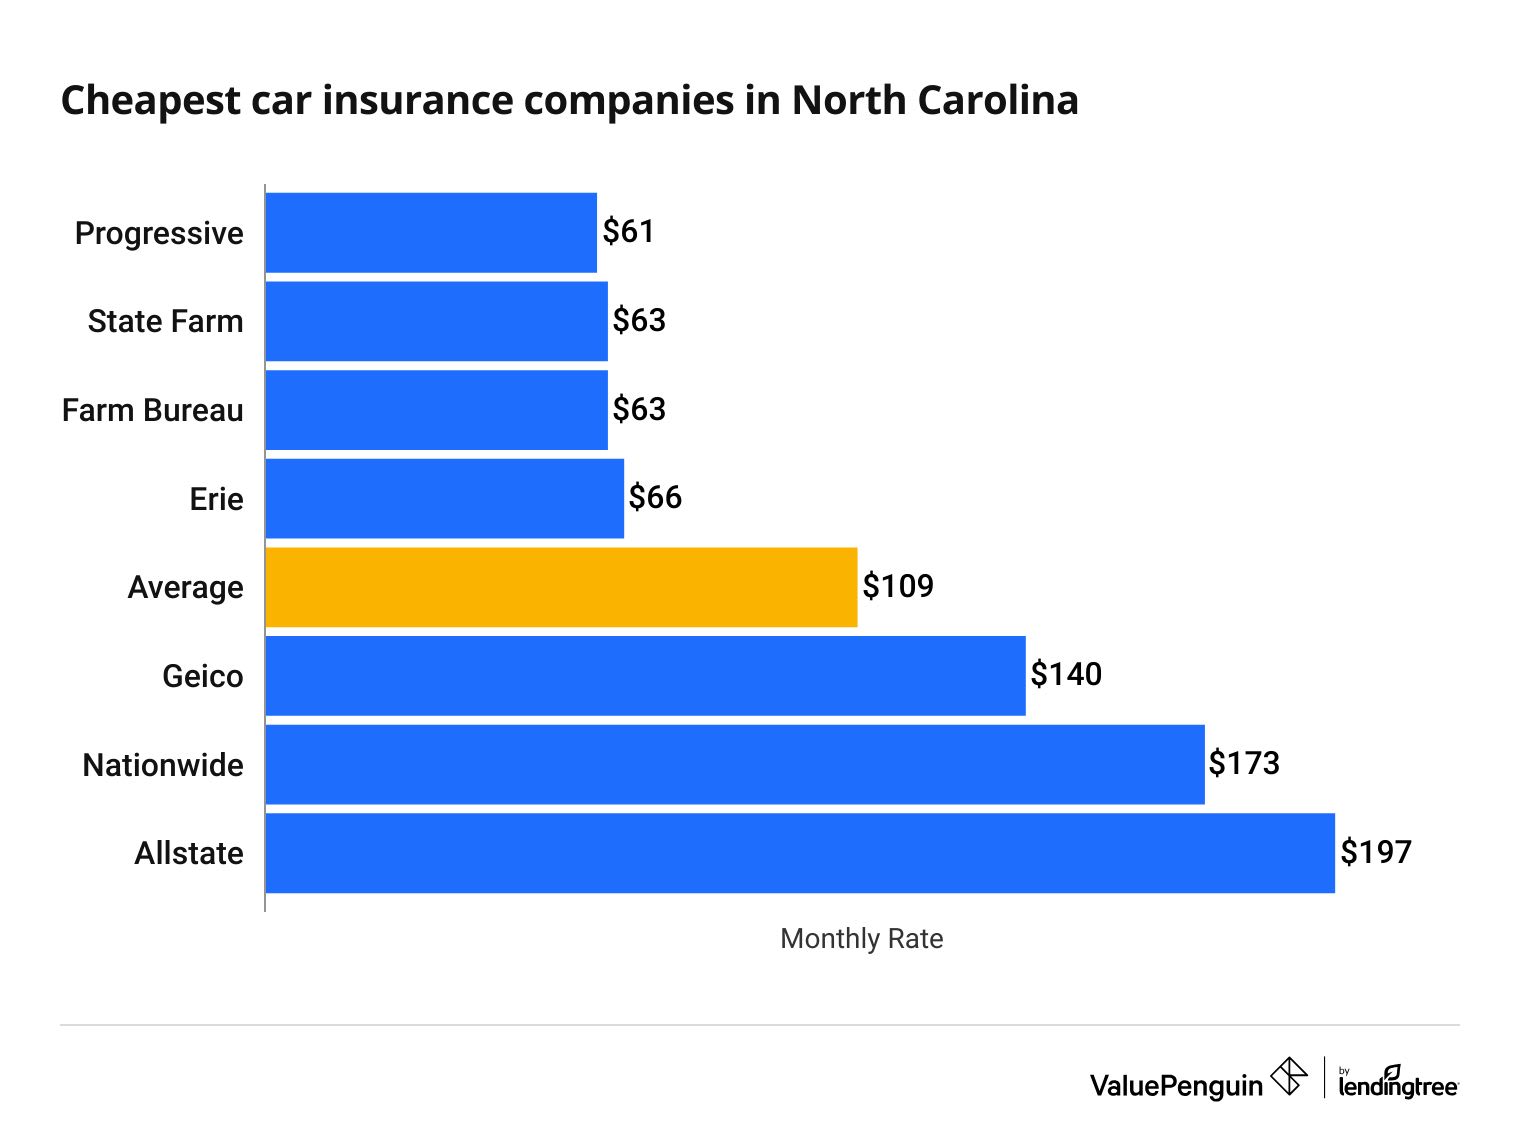
Did you know that state regulations can drastically impact your insurance premiums? In North Carolina, a maze of legislation and regulations directly influence how much you pay.
The state government plays a crucial role, ensuring that insurance companies operate fairly and transparently. But sometimes, this oversight can lead to increased rates. Let’s dive into the specific regulations and changes you need to know about.
State Regulations Influencing Insurance Rates in NC
In North Carolina, the Department of Insurance has the final say on rate changes proposed by insurers. This means they can reject hikes to protect consumers. BUT, here is the deal: this system can also slow down the introduction of competitive pricing.
Recent legislative changes have added new layers to rate determination. For instance, House Bill 629 introduced measures for more transparency, requiring insurers to justify their rate increases. This is a win for you because it keeps insurance companies in check.
Recent Legislative Changes Impacting Insurance Industry
New legislation is reshaping the landscape. The North Carolina Rate Bureau now plays a more significant role in defining rates for auto and home insurance. This encourages a more standardized approach, but it might not always favor the consumer.
Pro Tip: Stay updated with these legislative changes. They can directly affect your premiums and how you negotiate with your insurer.
The Role of Government Agencies in Regulating Rates
The North Carolina Department of Insurance is your ally when it comes to fair pricing. They regularly review and approve—or deny—rate changes requested by insurance companies. This ensures you’re not taken for a ride by sudden and unjustified hikes.
Additionally, they provide a platform for you to submit complaints and hold insurers accountable. Knowing that this watchdog exists can give you peace of mind as you navigate the complexities of insurance.
Final Summary
Now that you’re equipped with the insider knowledge and strategies to secure the best insurance rates in NC, it’s time to take action. Whether it’s bundling policies or practicing safe driving, every step you take brings you closer to significant savings. Keep this guide handy, and remember, finding the best rates is a journey, not a destination.
FAQ Section
What factors affect insurance rates in North Carolina?
Insurance rates in NC are influenced by factors such as location, age, driving history, and the type of coverage you choose.
How do insurance rates vary between cities in NC?
Insurance rates can vary significantly between cities due to factors like population density, crime rates, and traffic conditions.
What types of insurance are available in NC?
North Carolina offers various insurance policies including liability, comprehensive, and collision coverage.
How can I find the best insurance rates in NC?
Research, negotiate with insurance companies, and utilize online tools for rate comparisons to find the best insurance rates.
What are some strategies for lowering my insurance rates?
Maintain a good driving record, bundle policies, and consider increasing your deductible to lower insurance premiums.
